

Tracker Introduction
Ankura actively monitors wealth and asset management acquisitions and divestitures across the market to identify emerging themes, track the most active participants, and provide insights for advisors, platforms, and investors. The tracker provides a concise view into United States and Canadian market activity using publicly available information, S&P Capital IQ data, and Ankura analysis of Q2 2026 deals classified by announced date. Unless noted otherwise, figures reflect acquisitions of whole or majority stakes. This is the inaugural edition of the Wealth and Asset Management1 tracker, and part of the broader set of Financial Services trackers alongside Ankura’s Banking and Insurance M&A Trackers.
Q2 2026 Overview
Wealth and asset management M&A activity slowed slightly in Q2 2026. Tracked deal volume of 98 transactions descended from 116 in Q1 2026 and 107 in Q2 2025. The quarter came in just below the 12-quarter trailing average of approximately 99 deals and was the first quarter since Q3 2024 to fall below the 100-deal mark.
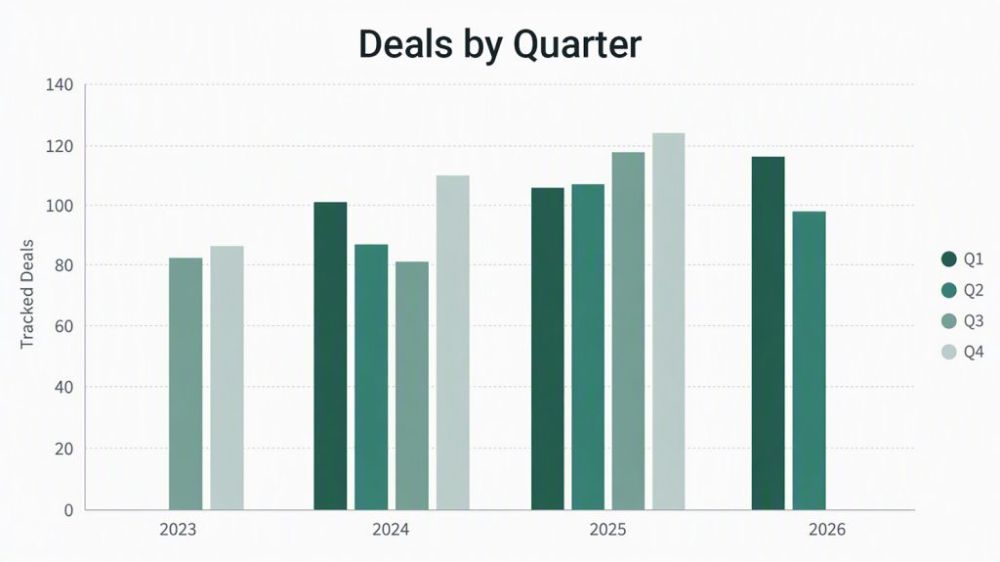
Transaction volumes in the first half of 2026 tracked closely with 2025 levels. The first half of 2026 produced 214 tracked deals, essentially flat against 213 in the first half of 2025 and up from 188 in the first half of 2024.
The Rising Involvement of Private Equity
Private equity (PE) participation has risen steadily over the past three years, from 18.3% of transactions in Q3 2023 to 39.8% in Q2 2026, with a peak of 43.2% in Q3 2025. In the current quarter, 39 of 98 transactions involved a PE sponsor. The PE strategy appears to be targeting smaller firms — of 11 tracked deals over $100 million of the first half of 2026, only one deal involved PE. For partial acquisitions in the wealth and asset management industry, PE participation has followed a similar trend. Through Q2 2026, 47% of partial acquisitions involved PE compared to just an average of 24% in 2024 and 33% in 2025.
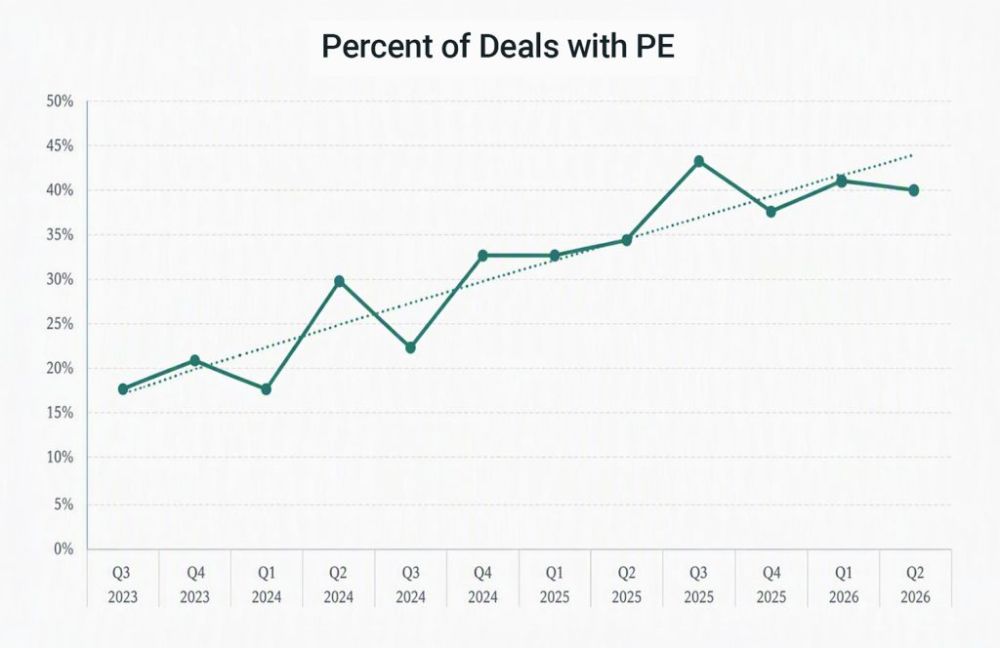
Wealth and asset management is particularly attractive to PE investors due to its recurring fee-based revenue, high client retention — driven by high advisor retention, and scalable back-office economics. In addition, the sector faces a lower regulatory capital burden than banking and insurance, allowing investors to pursue M&A strategies with greater flexibility and fewer balance sheet constraints.
Notable Deal Spotlight: Wellington Management Acquires Hartford Funds
Announced on June 3, 2026, Wellington Management agreed to acquire Hartford Funds Management Group from The Hartford (NYSE: HIG) for $1.9 billion. The deal was structured as $300 million in cash at closing plus payments based on after-tax cash generated over a seven-year period. The parties expect to close in the first quarter of 2027.
Hartford Funds manages approximately $160 billion of assets, of which Wellington already sub-advises roughly 83% of assets under a relationship beginning in 1978. Following close, the business is expected to integrate into Wellington’s U.S. Wealth business under the Wellington brand, adding approximately 200 client-facing professionals.
Wellington’s acquisition of Hartford Funds represents the formal integration of a multi-decade partnership into a single wealth management platform. By combining Wellington’s institutional investment capabilities with Hartford Funds’ established advisor network, the transaction expands Wellington’s reach in the U.S. wealth market. Additionally, it creates a more integrated operating model and enhances the firm’s ability to deliver investment, distribution, and servicing capabilities.2
Top Players: A Fragmented Field
A defining characteristic of wealth and asset management M&A activity is the variability of acquirers. Across 98 tracked transactions in Q2 2026, the most active buyers completed only three deals each, representing roughly 6% of quarterly volume. The fragmentation may suggest the market leadership remains available, leaving significant opportunity for well-capitalized acquirers to build scale through continued consolidation.
What to Watch for H2 2026
Looking ahead, financing conditions will continue to shape how aggressively sponsor-backed platforms pursue additional acquisitions. Higher borrowing costs would likely favor smaller add-ons that are easier to finance and quicker to integrate, while more favorable conditions would support larger platform trades. As we continue to track the sector through year-end, three key questions remain: whether wealth and asset management will consolidate at the lower-market level, whether transaction volumes will accelerate in the second half, and will PE activity continue to increase. Historically, Q3 sees the greatest volatility, with Q4 typically being the strongest quarter.
Closing
Wealth and asset management M&A outcomes are determined less at signing than in the execution that follows. Acquisition volume alone is not enough; realized value depends on disciplined integration planning, clear governance, synergy tracking, operating model alignment, technology enablement, and performance management. In a fragmented market, the differentiator is not finding targets but integrating them, and the failure modes are specific: advisor attrition, client transition friction, and unresolved custodian and technology consolidation.
Ankura supports acquirers and their investors across the M&A lifecycle, with a particular focus on turning acquisition strategies into executable value creation programs. We help firms evaluate integration priorities, align operating models, identify and track synergies, improve performance, and execute transformation initiatives that protect deal value and accelerate returns.
Ankura will continue to monitor developments across the wealth management market and provide periodic updates throughout 2026. We encourage readers to stay tuned for next quarter’s update and to see Ankura’s companion Banking and Insurance M&A Trackers. For questions regarding the dataset or specific transactions, please contact the Ankura team directly.
Footnotes
1 Deals tracked are classified as “Asset Management and Custody Banking” in S&P; this is inclusive of wealth management, institutional asset managers, fund GPs, BDCs, trust and administration providers, and retirement recordkeepers.
2 https://www.wellington.com/en-us/institutional/wellington-news/wellington-hartford-funds
The content of this article is intended to provide a general guide to the subject matter. Specialist advice should be sought about your specific circumstances.
[View Source]


